Tag: Payments

  • CBDC: The Future of Central Banks Digital Currency

    CBDC: The Future of Central Banks Digital Currency

    The Digital Dinar and Dirham: How CBDCs are Reshaping Finance in Egypt and Across Africa

    Central Bank Digital Currency is no longer a futuristic concept confined to whitepapers and economic forums; it is rapidly becoming a tangible reality across the globe. At its core, a Central Bank Digital Currency (CBDC) is a digital version of a nation’s official currency, issued and backed by its central bank. This isn’t like the money in your online banking app or the balance in your PayPal account. Unlike commercial bank deposits, a CBDC represents a direct liability of the central bank itself. It functions as a new, state-guaranteed form of digital money, designed to complement traditional cash and existing digital payment systems, but with the unique distinction of being a direct claim on the central monetary authority.

    This digital evolution of money promises to redefine the very fabric of our financial systems, and nowhere is its potential impact more significant than in dynamic and rapidly digitizing regions like Africa, with nations such as Egypt taking proactive steps to understand and potentially implement this transformative technology.

    What Exactly is a CBDC? Demystifying the Digital Currency

    To truly grasp the significance of a CBDC, it’s helpful to understand what it is not. The money most people use digitally today is commercial bank money. When you see a balance in your checking account, it represents a private liability of your bank—a promise from that institution to pay you the physical cash upon demand. A CBDC flips this model. It is the digital equivalent of a physical banknote; it is the central bank’s direct promise, making it arguably the safest form of digital money available, free from the risk of a commercial bank’s failure.

    CBDCs generally come in two forms:

    • Retail CBDCs: Designed for use by the general public for everyday transactions, much like cash. This is the type that could be used to buy groceries, pay bills, or send money to family.
    • Wholesale CBDCs: Restricted for use by financial institutions for settling large-value interbank transfers and securities transactions. This aims to make the financial system’s backbone more efficient and secure.

    The global drive towards exploring CBDCs is fueled by several factors, including the decline of cash usage, the rise of cryptocurrencies, the desire for greater financial inclusion, and the need for more efficient and resilient payment systems.

    The African Landscape: A Continent Embracing Financial Innovation

    Africa is a continent of contrasts, boasting some of the world’s fastest-growing economies alongside significant challenges in financial inclusion. According to the World Bank, a substantial portion of the adult population remains unbanked or underbanked. This is where the promise of CBDCs shines brightest.

    Several African nations are already leading the charge. Nigeria made headlines with the launch of the eNaira, becoming one of the first major economies in the world to roll out a retail CBDC. Ghana is actively testing the e-Cedi in a pilot phase, and South Africa is deeply involved in wholesale CBDC experimentation through Project Khokha. The East African Community is even exploring a regional CBDC to facilitate cross-border trade. This wave of innovation positions Africa not as a passive observer but as a active laboratory for the future of money.

    Egypt’s Strategic Foray into the World of CBDCs

    In North Africa, Egypt has emerged as a key player in the CBDC conversation. The Central Bank of Egypt (CBE) has recognized the profound potential of a digital currency and has initiated a careful and deliberate exploration process. The primary motivations for Egypt are multifaceted and strategically aligned with its national economic goals.

    First and foremost is the drive for financial inclusion. Despite progress, a segment of the Egyptian population still operates outside the formal banking system. A digital pound, accessible via a simple mobile phone, could bring these individuals into the formal economy, allowing them to save, pay, and borrow safely and efficiently.

    Secondly, a CBDC could dramatically enhance the efficiency of payments. It could reduce the cost and time associated with domestic money transfers and, crucially, streamline cross-border payments with trading partners and for the millions of Egyptians working abroad who send remittances home. Making remittances cheaper and faster would provide a direct boost to the national economy.

    Furthermore, the CBE sees a digital currency as a tool for improving monetary policy transmission. With a CBDC, the central bank could theoretically implement policy changes with greater speed and precision. It also offers a state-backed digital alternative to the growing wave of private cryptocurrencies, helping to maintain monetary sovereignty and stability.

    Navigating the Challenges on the Path to Digital Currency

    The journey to a fully realized CBDC is not without its hurdles. For Egypt and other African nations, significant challenges must be thoughtfully addressed:

    • Technological Infrastructure: Widespread adoption requires robust digital infrastructure, including reliable internet connectivity and electricity, which can be a challenge in remote or rural areas.
    • Digital Literacy: Ensuring that all citizens, not just the tech-savvy urban population, can understand and trust the new system is paramount.
    • Privacy and Security: A central bank-issued digital currency raises legitimate questions about user privacy and the potential for state surveillance, as well as the ever-present threat of cyberattacks.
    • Banking Sector Disintermediation: There is a risk that in a crisis, people might pull money out of commercial banks and into the perceived safety of a CBDC, potentially destabilizing the banking system.

    The Future is Digital

    The exploration of Central Bank Digital Currencies represents one of the most significant monetary innovations of our time. For Egypt and the broader African continent, the stakes are high. A successfully implemented CBDC has the potential to accelerate economic growth, foster greater financial inclusion, and create a more resilient and efficient payment ecosystem. While the path forward requires careful navigation of complex technological and social challenges, the proactive stance of the Central Bank of Egypt signals a clear recognition that the future of finance is undoubtedly digital. The work being done today will lay the foundation for a more inclusive and dynamic economic tomorrow.
    Stacks of coins with seedlings growing from them, beside a glass jar of coins
  • Soft POS Payment: Exclusive Egypt Solutions

    Soft POS Payment: Exclusive Egypt Solutions

    The SoftPOS Revolution: Transforming Payment Acceptance in Egypt

    SoftPOS technology is rapidly emerging as a game-changer in the global financial landscape, and Egypt is poised to be one of its most significant beneficiaries. As the nation charges forward with its digital transformation agenda, this innovative solution offers a powerful, accessible, and cost-effective way to bring more businesses and consumers into the formal digital economy. By turning everyday smartphones and tablets into secure payment terminals, SoftPOS is dismantling traditional barriers to electronic payments and empowering a new wave of merchants.

    What Exactly is SoftPOS?

    At its core, SoftPOS, or Software Point of Sale, is a revolutionary technology that allows a merchant to accept contactless payments directly on a standard, NFC-enabled mobile device—no additional hardware dongles or card readers required. A dedicated application transforms a smartphone or tablet into a fully functional payment terminal, capable of processing tap-to-pay transactions from contactless credit/debit cards, digital wallets like Apple Pay and Google Pay, and other NFC-based payment methods.

    This represents a significant leap from traditional mPOS (mobile Point of Sale) systems, which still rely on a separate physical card reader. SoftPOS eliminates that piece of hardware entirely, streamlining the payment process and drastically reducing the cost of entry for merchants seeking to accept digital payments.

    Why SoftPOS is a Perfect Fit for the Egyptian Market

    The Egyptian economy presents a unique set of circumstances that make the adoption of SoftPOS technology not just advantageous, but almost inevitable.

    • Driving Financial Inclusion: A primary goal for Egypt is to bring a larger segment of its population, including small merchants, freelancers, and service providers in the informal sector, into the banking fold. Traditional POS terminals can be expensive and require a credit check or business registration, which can be prohibitive. SoftPOS lowers these barriers, allowing virtually anyone with a smartphone to start accepting formal digital payments instantly.
    • Cost-Effectiveness: For micro-entrepreneurs, startups, and small businesses, every pound counts. The ability to use existing hardware (their phone) instead of investing in a dedicated terminal makes digital payment acceptance a financially viable option. This reduces initial setup costs and ongoing maintenance expenses.
    • Unmatched Agility and Mobility: Egypt’s vibrant economy is powered by mobile vendors, pop-up shops, delivery services, and freelance professionals. SoftPOS is the ultimate mobile solution, enabling payments anywhere there is a mobile data connection. A plumber can accept payment at a client’s home, a food truck can process orders faster, and a market stall owner no longer has to turn away customers who don’t carry cash.

    Navigating the Path to Secure and Widespread Adoption

    For SoftPOS to reach its full potential in Egypt, several key factors must be addressed to ensure a secure, reliable, and trusted ecosystem.

    • Robust Security and Certification: The most critical aspect of any payment technology is security. SoftPOS solutions must adhere to the strictest global security standards, such as those set by PCI SSC (Payment Card Industry Security Standards Council). This ensures that cardholder data is encrypted and protected throughout the transaction process, building essential trust with both merchants and consumers.
    • Regulatory Support and Collaboration: The Central Bank of Egypt (CBE) plays a pivotal role in shaping the future of digital payments. Creating a clear and supportive regulatory framework for SoftPOS will encourage innovation among fintech companies and financial institutions while safeguarding the integrity of the national payment system. Collaboration between banks, payment processors, and technology providers is key to a successful rollout.
    • Consumer and Merchant Education: Widespread adoption relies on familiarity and trust. Initiatives to educate both merchants on how to use the technology and consumers on the safety and convenience of tapping their phone or card on another phone will be crucial for overcoming initial hesitation.

    The Future of Payments is in Your Pocket

    The integration of SoftPOS into Egypt’s payment infrastructure is more than just a technological upgrade; it is a socio-economic catalyst. It empowers small businesses, formalizes transactions, and provides consumers with unprecedented convenience. As digital wallet usage grows and consumer behavior continues to shift away from cash, the demand for flexible payment solutions will only intensify.

    Looking ahead, we can expect to see SoftPOS technology integrated into a wider array of applications, from ride-hailing and food delivery apps to government service kiosks and event ticketing. This will create a seamless, omnichannel payment experience that defines a modern, digitally-forward economy.

    Conclusion: Embracing a Cash-Lite Future

    The momentum behind digital payments in Egypt is undeniable. SoftPOS stands at the forefront of this transformation, offering a pragmatic and powerful tool to accelerate the nation’s journey toward a cash-lite society. By leveraging the technology that is already in the pockets of millions, Egypt can unlock new levels of economic participation, drive growth for its smallest entrepreneurs, and build a more inclusive and resilient financial ecosystem for all. The future of payment acceptance in Egypt is not in a bulky terminal—it’s in the smartphone you already own.

    The forecourt and obelisk of the Grand Egyptian Museum in Giza under a blue sky
  • Payments Trends in 2025

    Payment trends in 2025

    The global payments landscape is experiencing unprecedented transformation in 2025, fueled by rapid digital growth and the way new technology is reshaping what customers expect. As this digital shift accelerates, the pressure is on payment providers and financial institutions to keep up with the trends that will define who stays competitive.

    Market Growth and Economic Impact

    The global payments market is projected to reach $788.06 billion in 2025, representing growth from $724.52 billion in 2024, with a compound annual growth rate of 8.8% expected through 2029. This surge traces back to the pandemic’s push toward digital and the lasting move away from cash.

    Digital wallet transaction volumes are forecasted to reach an astounding $17 trillion globally by 2029, up 73% from 2024 levels. In Egypt, the payments market stands at $20.6 billion in 2024 and is forecast to reach $31 billion by 2028, advancing at an 11% CAGR (compound annual growth rate).

    Digital Wallet Revolution and Consumer Adoption

    Digital wallets are leading the charge in payment innovation, in Egypt, digital payment use is climbing fast — nearly half of the population now reports comfort transacting online. This represents a significant shift in consumer behavior, with over 70% of global consumers now using digital payment methods, moving away from traditional cash transactions.

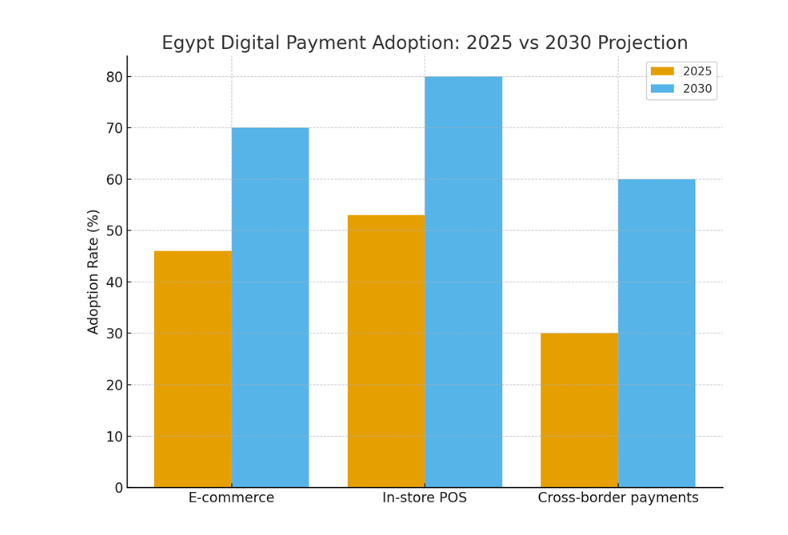
    The adoption rates vary significantly across different use cases:

    Payment Channel Egypt’s Adoption 2025 2030 Projection
    E-commerce ~46% 13–15% CAGR
    In-store POS ~53% ~75–85%
    Cross-border payments Growing >60%

    In Egypt, nearly 46% of internet users shop online weekly, while around 53% of SMEs have adopted digital payments. Cross-border flows remain central, with remittances exceeding $30 billion annually and steadily shifting toward digital channels.

    Emerging Payment Technologies

    Biometric Authentication

    Biometric payments are moving into the mainstream, with everything from fingerprints to facial and voice recognition tightening security. Early results suggest these tools can cut fraud by as much as 75% while making the checkout experience faster and easier.

    Artificial Intelligence and Machine Learning

    AI-powered payment systems are revolutionizing fraud detection and transaction processing. Advanced AI systems are achieving 30% reductions in fraud while improving transaction approval rates through intelligent routing and risk assessment

    Central Bank Digital Currencies (CBDCs)

    Central banks worldwide are advancing CBDC initiatives, with government-backed digital assets designed to improve financial inclusion and reduce cross-border transaction inefficiencies. These developments aim to provide faster cross-border payments and reduced reliance on traditional intermediaries

    Blockchain and Tokenization

    The tokenization market is experiencing explosive growth, projected to reach $4.13 billion in 2025 with a CAGR (compound annual growth rate) of 22.1%.

    Blockchain is gaining ground in B2B and commercial payments, where it’s being used to move money faster and with greater security.

    Regulatory Landscape and Compliance Challenges

    The payments industry faces significant regulatory changes in 2025, with major compliance deadlines reshaping operational requirements:

    Regulation Deadline Impact
    SEPA Instant Payments January 2025 Payment Service Providers must support instant payments
    Fedwire ISO 20022 Migration July 2025 New message format implementation
    PSD2, AML, KYC Directives Ongoing Enhanced authentication and data privacy
    Egypt Instant Payment Network (IPN) Regulations Egypt Instant Payment Network (IPN) Regulations Egypt Instant Payment Network (IPN) Regulations
    Bar chart of digital payment adoption in Egypt, 2025 against the 2030 projection: e-commerce about 46% rising to 70%, in-store POS about 53% rising to 80%, and cross-border payments about 30% rising to 60%

    Over 98% of financial institutions report rising compliance costs due to complex global regulations, creating pressure for infrastructure modernization. The regulatory timeline shifts highlight the challenges banks face in implementing complex technical changes within tight deadlines.

    Regional Trends and Cross-Border Payments

    Egypt’s Digital Surge

    In Egypt, mobile wallet transactions in Q2 2025 topped USD 19.63 billion, up from USD 11.41 billion in the same period the year before — a massive 72% year-over-year increase.

    Meanwhile, about 64% of Egyptians reported higher use of digital payments in 2024, and 35% had adopted wallets.

    The Rise of Embedded Finance

    Embedded finance is transforming how payments are integrated into business operations, with experts anticipating $6.5 trillion in payments processed through embedded channels by 2025. This trend represents a shift from standalone payment solutions to integrated financial services within business ecosystems.

    Future Outlook and Strategic Implications

    The payments industry in 2025 is characterized by rapid technological advancement, regulatory complexity, and evolving consumer expectations. Key strategic priorities for industry stakeholders include:

    1. Digital Wallet Integration: Essential for competitive positioning
    2. Security Investment: Biometric and AI-powered solutions
    3. Regulatory Compliance: Proactive preparation for changing requirements
    4. Consumer-Centric Design: Focus on convenience, rewards, and seamless experiences
    5. Partnership Strategy: Collaboration with technology leaders and fintech innovators

    Security Innovations and Fraud Prevention

    Payment fraud losses have surpassed $40 billion globally, making security innovations critical for industry sustainability. Key security developments include:

    • Biometric Authentication: Up to 75% fraud reduction capability
    • AI-Powered Fraud Detection: Real-time risk assessment and prevention
    • Tokenization: Enhanced data protection and privacy compliance
    • Advanced Encryption: Multi-layer security protocols

    In conclusion,

    The payment trends of 2025 reflect a fundamental transformation of the financial services landscape. Digital wallets, emerging technologies, and changing consumer behaviors are reshaping how transactions are conducted globally. Organizations that embrace these trends, invest in security innovations, and maintain regulatory compliance will be best positioned to thrive in this dynamic environment.

    As we move toward an increasingly digital future, the payments industry must balance innovation with security, convenience with compliance, and global reach with local requirements. The successful navigation of these trends will determine the leaders in tomorrow’s financial ecosystem.

    Sources

    • Google Trends data (digital wallet searches)
    • Visa consumer & industry reports (digital wallets, biometrics, authentication trends)
    • Discover Global Network research (payments) consumer biometrics, fraud prevention, real-time
    • Nexi Group mobile payment reports (Italy, Nordics, sustainability)
    • Worldpay forecasts (global real-time transactions, green payments)
    • J.P. Morgan payment insights (cross-border flows, Wire 365, $10T daily processing)
    • LexisNexis fraud prevention and embedded payments studies
    • FedNow and RTP Network (instant payments adoption, ISO 20022)
    • Central Bank of Egypt (IPN/Instapay regulations, adoption)
    • Mordor Intelligence (Egypt digital payments & e-commerce forecasts)
    • PwC / Egyptian consumer surveys (digital payment adoption rates)
    • Thunes & Arab News (Egypt remittances)